Home › Free › Net worth tracker app for Australia: track what you own and owe
Net worth tracker app for Australia: track what you own and owe
Net worth is one of the simplest money numbers there is, and one of the most useful to track over time. It is everything you own minus everything you owe. You do not need to be wealthy to track it. In fact, it is often most motivating when you are paying down debt, because the number climbs every time a balance drops. This guide explains how to track net worth in Australia, what to include, and how a private, offline net worth tracker app can help.
What counts as an asset
Assets are things with a money value you could reasonably put a number on. For most Australian households, that includes:
- Cash and savings: everyday accounts, high-interest savings, offset accounts and term deposits.
- Superannuation: your super balance from your fund's app or statement. Many people track it separately because the ATO says you can generally only withdraw it once you turn 65, or reach your preservation age and retire (or start a transition to retirement income stream), unless an early access condition applies (ATO). It is still yours.
- Investments: shares, ETFs and managed funds at current market value.
- Property: your home or an investment property, at a realistic estimate. Be conservative and update it rarely.
- Vehicles: a car is an asset, but it loses value. Use a realistic resale figure, not what you paid.
- Other: anything substantial you could sell, such as a caravan or boat. Skip everyday belongings, which usually make the number noisy rather than useful.
What counts as a liability
Liabilities are amounts you owe:
- Your home loan balance (minus any offset, if you have counted the offset as an asset, so you do not double count).
- Car loans and personal loans.
- Credit card balances.
- Buy now, pay later balances.
- Your HELP (student loan) balance. The ATO applies indexation to it on 1 June each year (to the part unpaid for more than 11 months), so many people list it on its own line (ATO).
- Money owed to family or friends, if you plan to repay it.
How to track your net worth in four steps
- List every account once. Write each asset and liability with its current balance.
- Pick a tracking day. The first of the month or the day after payday works well. Consistency matters more than frequency.
- Update balances, not the list. Each time, you only change the numbers.
- Look at the trend. Markets move, and property estimates are rough, so a single month can jump up or down. The line over a year is what tells the story.
Why track net worth at all?
A budget tells you where this fortnight's money goes. Net worth tells you whether all those fortnights are adding up. It joins the dots between paying off a credit card, building an emergency fund and growing super. It also keeps you honest: a new car on finance might feel like progress, but net worth shows the loan next to the asset.
It is also encouraging. When you are paying off debt, your net worth can be negative for a while. Watching it move from negative towards zero is a real milestone, and one that a bank balance alone will not show you.
Spreadsheet or app?
A spreadsheet works fine if you enjoy building one. The downsides are that formulas break, charts take effort, and it is easy to stop updating. Many net worth apps fix that by linking to your bank accounts, which is convenient but means sharing your bank login or open banking data with a third party, and often paying a subscription.
We took a different approach. Our apps are single HTML files that run offline in your browser. You type in your balances, or import a bank CSV file if you want to, and the data stays on your device. There is no bank login and no subscription.
A worked example (made-up numbers)
Say you have $5,000 in savings, $40,000 in super and a car worth about $12,000. That is $57,000 in assets. You owe $8,000 on the car loan, $2,000 on a credit card and $15,000 on HELP, so $25,000 in liabilities. Your net worth is $57,000 − $25,000 = $32,000. Without super it would be −$8,000, which is why some people track both lines. These numbers are only an illustration.
 Money HQYour whole money life in one browser app: payday-aware budget, bills calendar, savings goals, debt payoff and net worth.See the app →
 Savings Challenge TrackerFun tick-off savings challenges: 52-week, reverse, 26-fortnight, 100 envelopes, Christmas and more, with badges.See the app →
Tips for an honest net worth number
- Be conservative with property and cars. Overestimating feels nice but makes the trend less useful.
- Use the same sources each time. The same valuation approach every month keeps comparisons fair.
- Do not double count offset accounts. Either list the offset as cash and the full loan as a liability, or net them, but not both.
- Track super separately if it helps. Some people like a "net worth without super" line to see what they can actually reach today.
- Do not compare yourself with others. Age, location, housing costs and life stage change everything. Compare yourself with you, a year ago.
Net worth alongside your budget
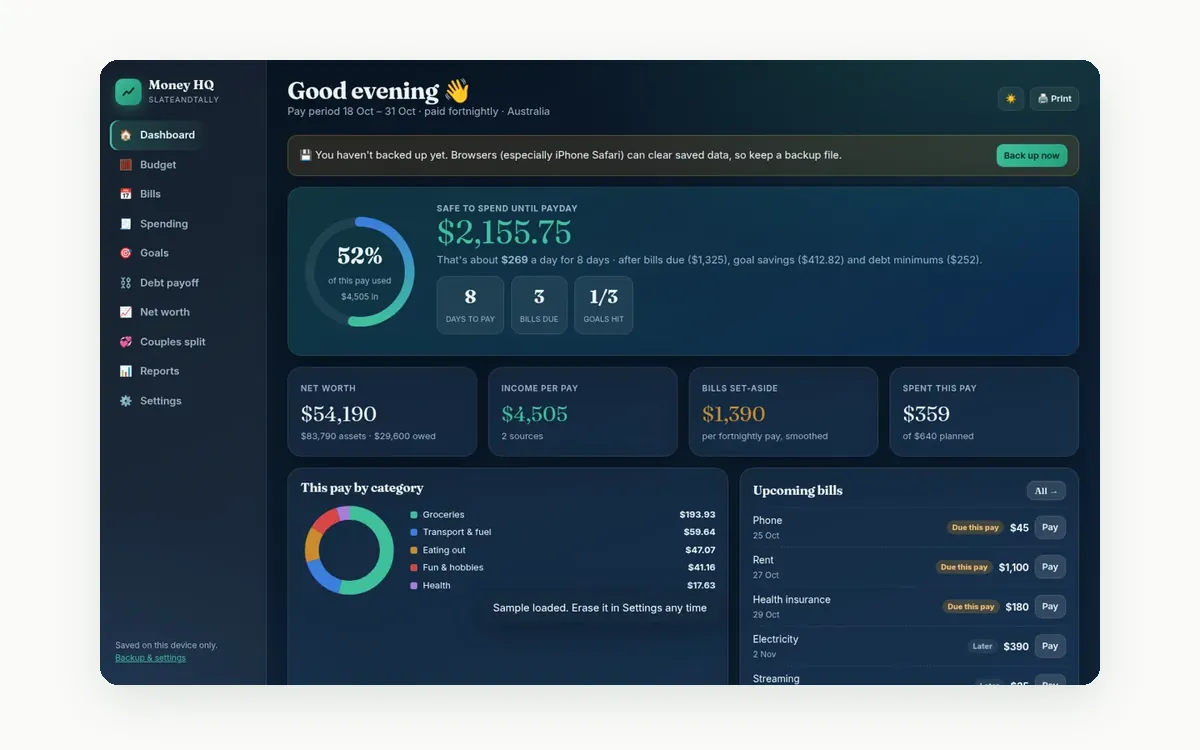
Net worth works best next to a budget, so you can see how day-to-day choices move the big number. That is why we built net worth into Money HQ, our all-in-one app, rather than selling it on its own. Your fortnightly budget, bills calendar, savings goals and debt payoff all sit next to the net worth dashboard.
A payday-aware budget (weekly, fortnightly or monthly), bills calendar, savings goals, debt payoff and net worth dashboards, plus bank CSV import, print to PDF and dark and light themes. It works offline in your browser, your data stays on your device, and there is no bank login. Secure checkout via Payhip.
See the Money HQ app · A$59
Just want the budget part for now? Start with the Fortnightly Budget app (A$29), or browse all our budget apps. You can also read why we built our budget apps to work offline.
Frequently asked questions
How do I calculate my net worth?
Add up everything you own (cash, super, investments, property, vehicles) and subtract everything you owe (home loan, car loan, credit cards, BNPL, HELP). The result is your net worth.
Should I include super in my net worth?
Many Australians do, because it is your money. Some also track a figure without super, because the ATO says you can generally only withdraw it once you turn 65, or reach preservation age and retire. Source: {a('https://www.ato.gov.au/individuals-and-families/super-for-individuals-and-families/super/withdrawing-and-using-your-super/super-withdrawal-options','ATO')}.
How often should I update my net worth?
Monthly or quarterly is plenty. Pick a fixed day and stick with it, and focus on the trend over a year.
Does Money HQ connect to my bank?
No. There is no bank login. You type balances in or import a bank CSV file, and your data stays on your device.
Is a negative net worth bad?
It is common, especially with student loans or early in a home loan. What matters most is the direction it is moving.
General information only, not financial advice. Asset values are estimates. For advice about your situation, speak with a licensed financial adviser. Moneysmart (moneysmart.gov.au) has free government guidance.